Building Resilience When the Playbook Keeps Changing
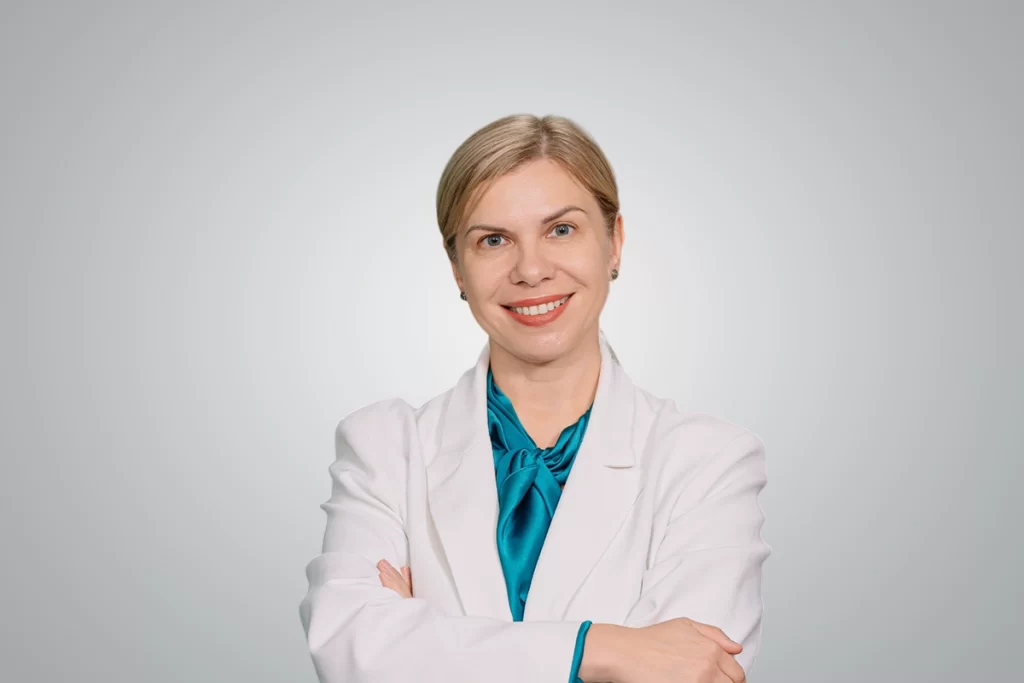
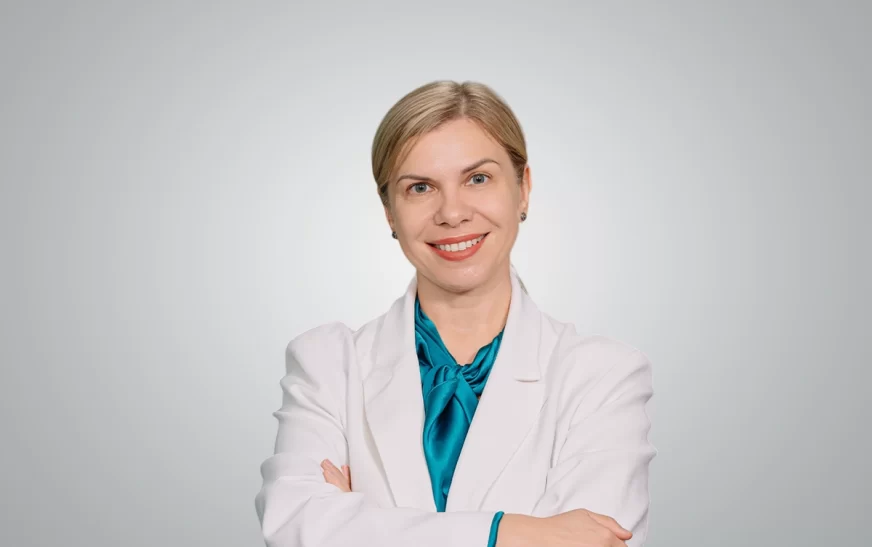
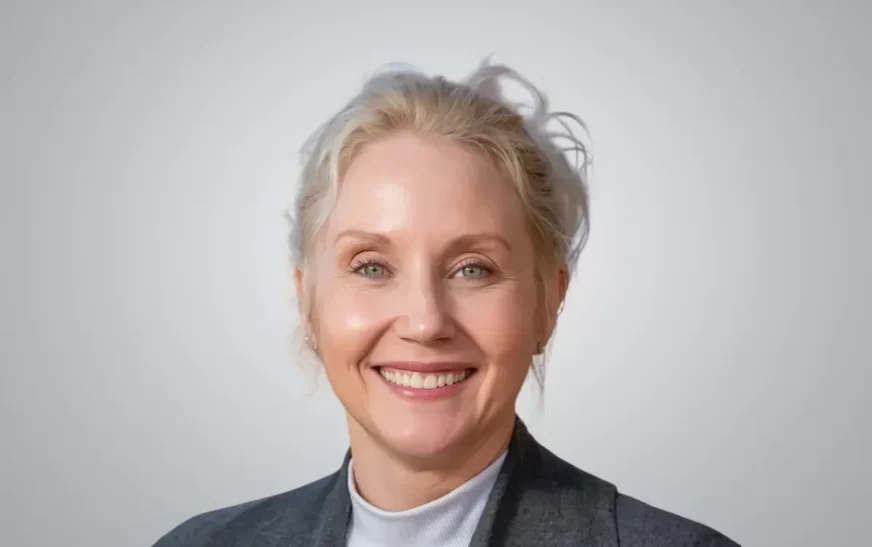
Olena Khlon
General Director
SFinance Consumer Credit Finance Company Ltd.
Building Resilience When the Playbook Keeps Changing
Olena Khlon
General Director
SFinance Consumer Credit Finance Company Ltd.
Olena Khlon-Best CXOs in Asia 2026
Olena Khlontook charge at SFinance in August 2022. What followed was a series of challenges that would put both the company and its leadership to the test. The company, formerly known as SHBFinance, faced a liquidity crisis, collection challenges in 2023, the impact of Typhoon Yagi in 2024 and severe capital constraints in 2025.
Each setback called for a different response, but Olena Khlon’s approach remained grounded in the same principles: stay close to the team, keep improving processes and make the hard decisions when circumstances leave little choice. The experience taught her that resilience is not about predicting every disruption. It is about building a team that can respond when plans change and having the discipline to protect the company’s stability, even when that requires difficult short-term decisions. That approach helped SFinance navigate several consecutive challenges and deliver strong performance in the first half of 2026.
When TradeFlock interviewed Olena Khlon, General Director, SFinance Consumer Credit Finance Company Ltd., she spoke about the turning points that shaped her leadership and the lessons she took from navigating some of the company’s most difficult years.
As digital lending and instant credit grow, how are customer choices and behaviour changing?
Customers today are increasingly seeking what we call “hyper-personalisation at scale”. They no longer want a standard loan; they expect seamless financial solutions that anticipate their needs and fit their lifestyles. At SFinance, we have embraced this shift, growing our digital business from 5% to 20% of total revenue.
A key behaviour we watch is how customers balance speed with trust. They want instant access to credit, but also expect transparency, security, and a seamless experience. For us, this means moving beyond simply providing loans to building timely, personalised, and trusted financial relationships. Ultimately, customer behaviour shows whether they see us as a reliable, long-term financial partner or simply a transactional tool they can move away from after one use.
How can lenders turn customer trust into a lasting competitive advantage?
I believe lasting customer trust is built on three things: transparency, reliability, and human support. Technology can make financial services faster and more personalised, but for consumer finance customers in Vietnam, technology alone is not enough. Many are still building digital confidence, making “human tech”, technology supported by real human interaction, essential.
Customers need to know they can reach someone when they have questions, face difficulties, or need guidance. For us, this means combining digital convenience with human reassurance: being transparent about products and terms, keeping our commitments, and ensuring customers never feel they are dealing with technology alone. This builds trust that lasts.
What field outside your profession could have shaped you as a leader, and why?
My dream was to become a doctor, and at one point I considered leaving banking to pursue medicine. I am ultimately glad I stayed in banking. Medicine taught me, even from a distance, an important leadership principle: sometimes you must hurt to heal.
During periods of change or crisis, difficult decisions can be necessary to improve a situation. Responsibility, self-discipline, and the courage to make those decisions are qualities I continue to strengthen as a leader.
Where do AI and alternative data offer the biggest opportunity for lenders, and what risks come with them?
I see the greatest opportunity in using AI and alternative data to understand customers better and make faster, more accurate financial decisions. These tools can help lenders reach customers who may be underserved by conventional models while personalising products and credit offerings around actual needs.
However, greater access to data brings greater responsibility. Privacy, data security, algorithmic bias, and limited transparency in AI-driven decisions are risks the industry cannot overlook. Technology should never undermine customer trust.
The future is not about AI replacing people but empowering them to make better decisions using data responsibly and transparently. Innovation must also operate within regulatory boundaries. In 2025, we allocated 80% of our resources to strengthening risk management and compliance, including upgrading our core banking system and adopting a zero-tolerance approach to fraud. These foundations are critical to using alternative data safely and ethically.
As consumer finance companies grow, which is hardest to protect: risk, regulation, or financial inclusion?
I believe the right balance starts with three principles: safe, smart, and speedy, in that order. Speed matters, but it should follow a safe and intelligent foundation. We experienced this in 2024, when we adjusted our risk appetite and consciously accepted slower growth to strengthen and standardise our systems before accelerating again. It was a deliberate choice to prioritise sustainable growth over short-term results.
Financial inclusion is also about helping customers understand how to manage credit responsibly. That is why we invest in financial and risk education both within and outside the organisation. We equip employees with stronger awareness while helping customers understand financial management, the benefits and consequences of borrowing, and the risks of over-indebtedness.
For me, the hardest priority to protect as growth accelerates is safety. When safety and intelligence come first, speed becomes a natural outcome of a strong foundation rather than something we have to chase.